The DFS outlines planned annual production of 50,000 tonnes of graphite concentrate at 90% LOI1000 grade. The company said proposed sales include classified products for drilling fluids, lubricants and friction products, unclassified concentrate for foundry and recarburizer markets, and concentrate intended for its planned downstream battery-materials business.
Sarytogan reported an Ore Reserve of 14.5 million tonnes at 29.1% total graphitic carbon, including 2.5 million tonnes of Proved and 12.0 million tonnes of Probable Reserve. It said 8.5 million tonnes of higher-grade material is scheduled for processing over a nominal mine life exceeding 50 years.
According to the company’s DFS assumptions, the upstream project has estimated pre-tax NPV8 of US$132.7 million, initial capital expenditure of US$80.5 million, operating costs of US$364 per tonne of concentrate and an IRR of 19.8%. These estimates are based on an assumed average concentrate selling price of US$805 per tonne.
The company said further approvals, including approvals for the processing plant, tailings storage facility and other infrastructure, are to be progressed before construction. It also said an ESIA addendum is a key prerequisite to financial close, while no binding offtake agreements are in place and required project capital has not yet been secured.
Source: Download SGA official ASX announcement, 2026-10-21.
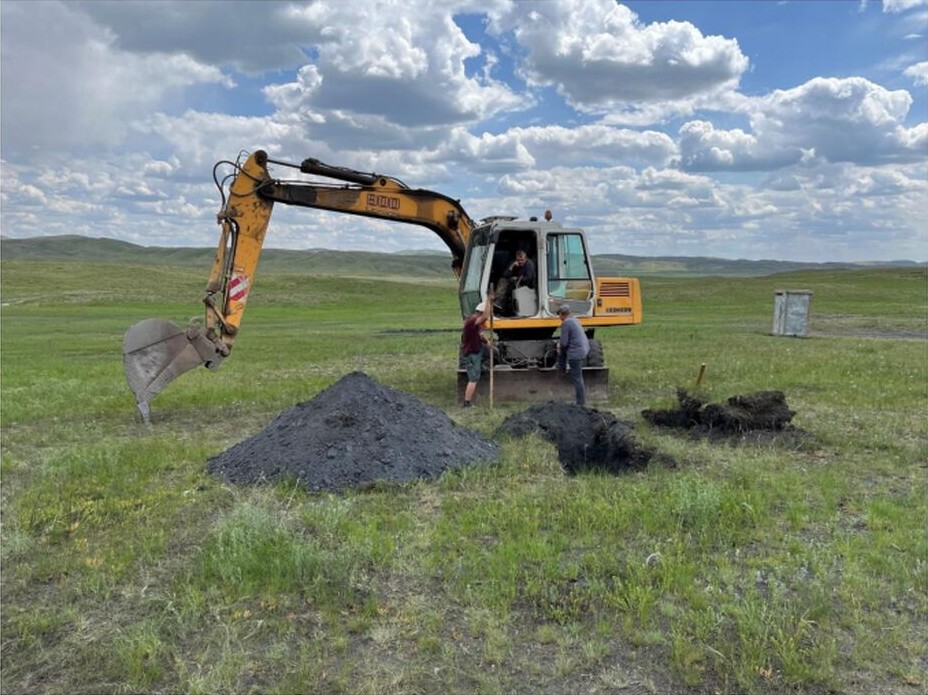
Exploration test pit at the Sarytogan Graphite Deposit, from Sarytogan Graphite’s company announcement dated 21 October 2026.