The PFS reports a maiden Probable Ore Reserve of 151.25 million tonnes at 99.25% SiO2 for the Si2 deposit. Diatreme said the reserve underpins an initial 25-year mine life, with the study considering a 3 Mtpa Phase 1 case and a potential expansion to 5 Mtpa from year three, subject to market conditions and product demand.
For the Phase 1-only case, Diatreme projects pre-tax NPV of A$1.29 billion and pre-tax IRR of 36%, based on A$443.5 million in construction capital including contingency. The expanded Phase 1 and Phase 2 case is projected to deliver pre-tax NPV of A$2.419 billion and pre-tax IRR of 46%, with an additional A$38.5 million of expansion capital. The forecast assumptions include an average silica sand price of US$55/t FOB, an AUD:USD exchange rate of 0.68 and an 8% real unleveraged discount rate.
The company said the PFS remains preliminary and that completion of a definitive feasibility study, outstanding approvals, agreements and financing are required before a final investment decision. Diatreme is targeting DFS completion in the third quarter of 2028 and a final investment decision in the fourth quarter of 2028. Project financing has not been secured, while access arrangements at the Port of Cape Flattery, mining leases, environmental approvals, offtake and native title agreements remain among key project requirements.
Source: Download DRX official ASX announcement, 2026-10-15.
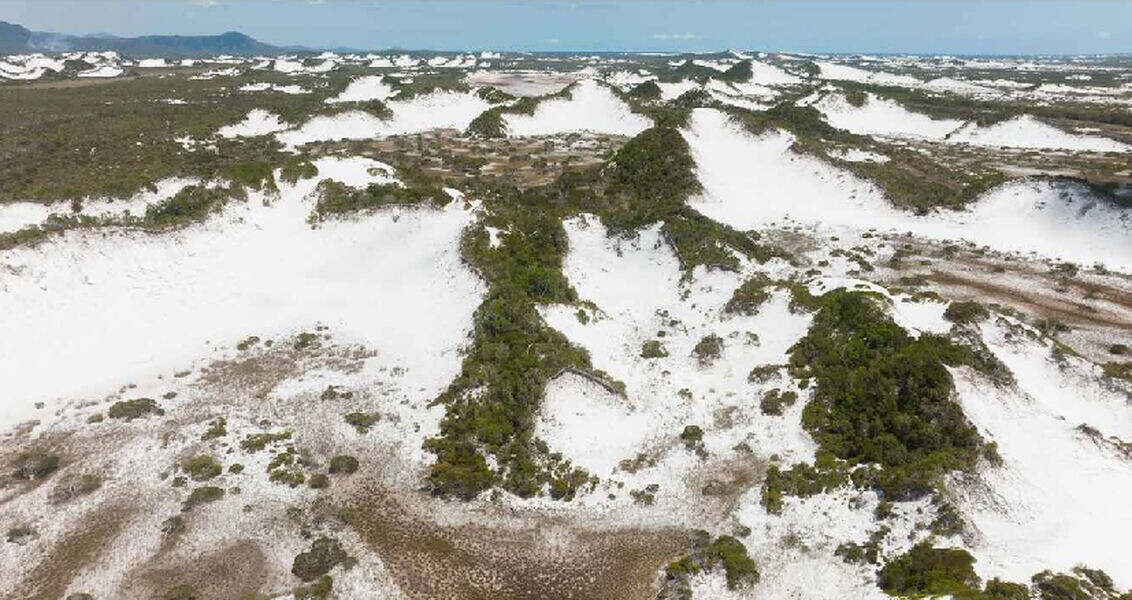
Silica sand dune landscape shown in Diatreme Resources' Northern Silica Project Pre-Feasibility Study announcement dated 15 October 2026.